Gold holds a unique legal and religious status for Muslim investors. It is recognized as a store of value under the Quran and is subject to zakat. When acquired in accordance with Sharia, it is among the most compliant assets in Islamic finance. However, the legal requirements governing gold transactions under Sharia are stringent. The range of gold investment products available to investors in Kenya spans from fully compliant to clearly prohibited. Non-compliant products often coincide with fraudulent schemes that have caused significant financial losses for foreign investors in Nairobi.
This material is intended as general legal and educational guidance; for advice tailored to your specific circumstances, including any questions arising in court or other legal forums, you should consult qualified Sharia scholars in conjunction with your legal advisers.
Why Gold Has Special Rules in Islamic Law
Gold and silver are classified as ribawi items, currencies, in the classical analysis. That classification triggers two rules with no parallel in ordinary goods:
- Equality in kind: When gold is exchanged for gold, the transaction must involve equal weight and must be settled within the same session. There can be no extension of credit, no deferral of settlement, and no advantage in weight.
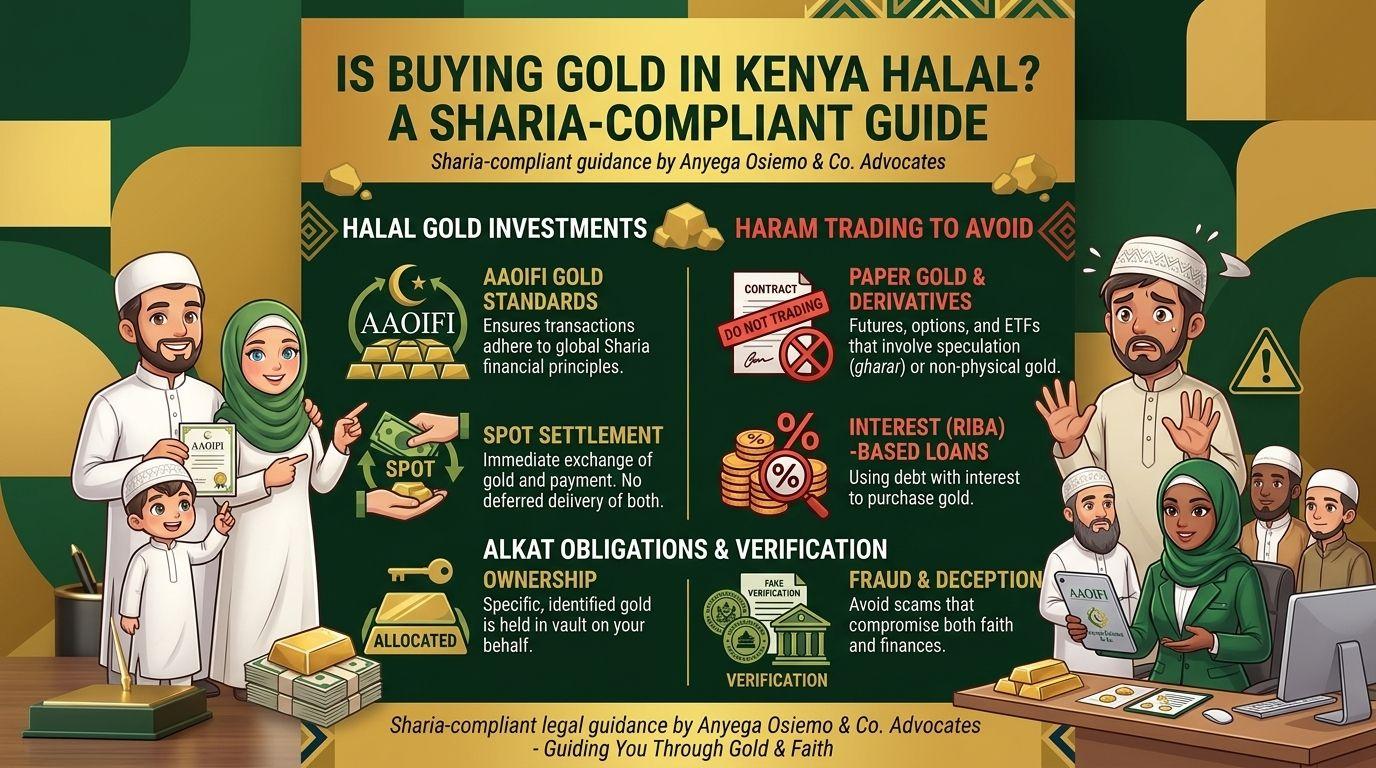
- Spot settlement with currency: In transactions where gold is purchased with money, which is the standard scenario, the exchange must be effected immediately. Both payment and transfer of possession must be completed within the same contractual session or within the customary short settlement period.
These rules exist to close the door on riba (unlawful increase) that can hide within what appears to be trade. They also explain why most "gold investment" structures marketed to foreigners are non-compliant: anything leveraged, derivative, deferred, unallocated, or paper-based falls into the prohibited zone. AAOIFI's Shariah Standard on Gold codifies the modern consensus, including the requirements that transactions be settled on a spot basis and that ownership be fully allocated to the buyer <REF>cite✦tools://web_search:79#0:~text=Gold must be traded on a spot (hand-to-hand) basis...the gold has to be fully allocated</REF>.
The Compliant Route: Physical, Allocated, Spot-Settled
A gold purchase in Kenya that is compliant with Sharia must satisfy four essential elements. Failure to meet any of these requirements renders the transaction non-compliant:
1. Real, specific metal. Bar or coin, serialized, identifiable, with a recognized assay. "Exposure to gold," an account balance "backed" by a pool, is not ownership of gold; it is a claim on a counterparty. Under the AAOIFI framework, constructive possession requires full allocation to the buyer <REF>cite✦tools://web_search:79#0:~:text=In the case of constructive possession, the gold has to be fully allocated</REF>. Unallocated pool accounts fail this test.
2. Spot settlement. Payment and transfer of possession, whether by physical delivery or documented transfer into allocated custody, must occur within the contract session or the customary settlement period. While some schools of Islamic jurisprudence recognize certain deferred payment structures (such as specific murabaha arrangements for gold), the prevailing standard for investors is to purchase for cash and take immediate delivery.
3. No leverage, no derivatives. Margin trading, gold CFDs, futures, options, and XAU/USD "trading accounts" are built on riba (leverage) and maysir (speculative character). The scholarly consensus treats leveraged gold speculation as impermissible. If a product's pitch involves "trading gold without owning it," it is non-compliant.
4. Genuine custody and transparent fees. Storing allocated gold with a professional custodian under a documented safekeeping (wakalah) agreement is compliant, provided that the metal remains your property, the custodian acts as your agent, and the fee is clearly identified as a service charge. The custody agreement must specify that the metal is allocated and segregated and include an audit trail to verify this arrangement.
Spot settlement. Payment and transfer of possession, whether by physical delivery or documented transfer into allocated custody, must occur within the contract session or the customary settlement period. While some schools of Islamic jurisprudence recognize certain deferred payment structures, the prevailing and undisputed standard for investors is to purchase for cash and take immediate delivery.
No leverage, no derivatives. Margin trading, gold CFDs, futures, options, and XAU/USD "trading accounts" are built on riba (leverage) and maysir (speculative character). The scholarly consensus treats leveraged gold speculation as impermissible. If a product's pitch involves "trading gold without owning it," it is non-compliant on both fronts.
Genuine custody and transparent fees. Storing allocated gold with a professional custodian under a documented safekeeping (wakalah) agreement is compliant, provided that the metal remains your property, the custodian acts as your agent, and the fee is clearly identified as a service charge. The custody agreement must specify that the metal is allocated and segregated and include an audit trail to verify this arrangement.
The Products to Avoid and Why They Fail Twice
- Unallocated "gold savings" accounts: no allocated metal, a claim on an institution fails the ownership test, and exposes you to that institution's solvency.
- Leveraged and derivative gold: riba and maysir, scholarly consensus against, and statistically ruinous for retail buyers.
- "Gold investment plans" with promised returns: any product promising yield on gold is either lending your metal (riba) or running a scheme. Promised returns on a store-of-value asset are the signature of fraud, the same advance-fee, "guaranteed return" architecture documented in our gold scam recovery guide, dressed in Islamic vocabulary. A scheme that quotes the Quran while selling unallocated paper is a worse scandal than an honest haram trade.
- Fractional bar schemes without true allocation: a "share" in a bar you cannot identify, settle, or take delivery of fails at both spot settlement and ownership.
It is important to recognise that each of the structures described above not only contravenes Sharia but also falls outside the protections afforded to buyers under Kenyan law. In practice, the requirements for Sharia compliance and legal safety are identical, though qualified legal advisers should assess any issues arising in court or other legal forums.
Buying Physical Gold in Kenya: The Combined Halal and Legal Checklist
Kenya: Verify the dealer: Confirm the company’s registration through eCitizen or the Business Registration Service (BRS), verify the mineral dealer's license, and check any claimed mineral rights on the Mining Cadastre Portal. Engaging with a licensed and verifiable counterparty is a prerequisite for legal compliance and ethical conduct. Verify the metal: Arrange for an independent assay at a laboratory of your selection, ensuring proper sampling procedures and an unbroken chain of custody. The purity and weight of the gold must correspond precisely to what is being purchased. Overpricing impure metal constitutes both gharar (uncertainty) and fraud.
- Structure spot settlement: Ensure that payment and delivery, or transfer into allocated custody, occur within the same contractual session and are fully documented. Documentation should include the invoice, assay report, serial numbers, and custody receipt.
- 2. Document allocated custody: Where gold is stored with a professional custodian, ensure that a wakalah-style agreement is in place. This agreement should identify your specific bars, confirm segregation, and grant you the right to inspect and receive delivery upon demand.
- 3. Handle export correctly: Kenya's export regime operates exclusively through official channels. Any purported 'export fee' payable to a private individual or entity is unlawful and indicative of fraudulent activity. If the gold is to be exported, ensure that the lawful export process is followed and that all steps are properly documented.
- 4.Record for zakat and inheritance: keep purchase records, including weight, purity, cost, and storage location. Your gold is zakat-liable and will form part of your estate; the records serve both obligations.
Zakat on Your Gold Holdings
Gold held as wealth attracts zakat when it reaches the nisab, approximately 85 grams of gold content held for one lunar year, at the standard rate of 2.5%. The practical questions investors face are:
- Purity is determinative: The nisab threshold is measured by the actual gold content. Calculations should be based on the assay results rather than the bar's gross weight.
- Valuation date: Zakat is assessed on the current market value of the gold holding as of the zakat anniversary date, rather than the original purchase price.
- Intention matters: gold held for personal use (jewelry, in some schools' view) may be treated differently from gold held as an investment. Positions differ among schools — take guidance from your scholars.
- Records facilitate compliance: The same register that secures your estate also simplifies zakat calculations. It is essential to keep these records up to date.
Estate Planning for Muslim Gold Investor
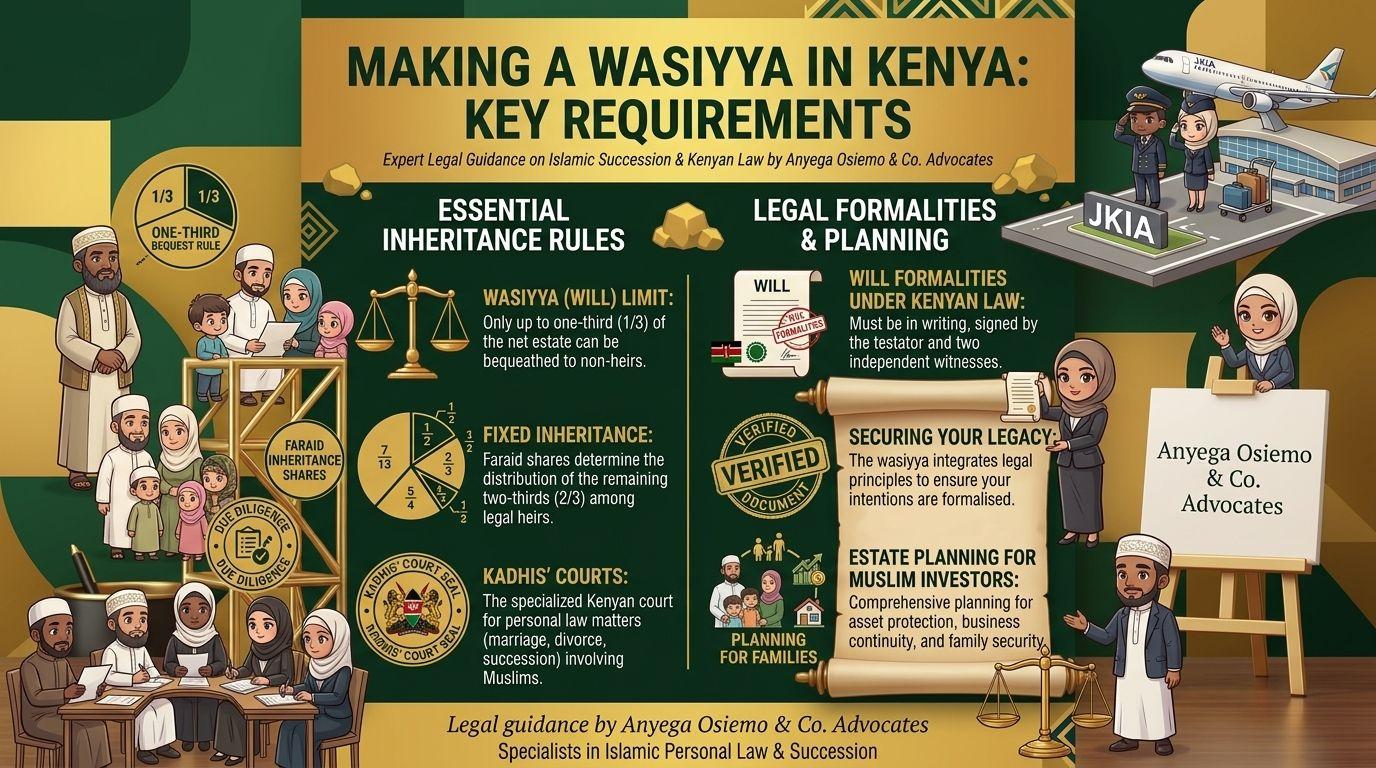
,Gold falls under the Islamic inheritance rules (faraid), with the wasiyya, the testamentary bequest, capped at one-third of the estate and directed away from the fixed Quranic shares unless the heirs consent. For investors holding Kenyan gold or other Kenyan assets, the practical architecture comprises a formal wasiyya executed in accordance with Kenyan will formalities, a documented asset register identifying bars and custody arrangements, and coordination between your Sharia advisers and Kenyan counsel. Our companion guides on wasiyya under Kenyan law and on inheritance for foreign spouses cover the mechanics; the register described in our crypto estate planning guidance works identically for physical metal.
A Worked Example: The Five-Kilogram Purchase
Consider the following example: A Gulf-based family office directs the purchase of five kilograms of investment-grade gold bars in Nairobi, to be held in allocated custody. The compliance process is as follows: the dealer is verified through the Business Registration Service and licensing records; the bars are independently assayed at a laboratory chosen by the buyers; settlement occurs on the same day by bank transfer, with delivery of serial-numbered bars into segregated custody under a documented safekeeping agreement that includes inspection rights; all documentation, including invoices, assay reports, custody receipts, and insurance schedules, is provided to the family's advisers. Zakat records are established on the settlement date. There is no use of leverage, no pool account, no promised yield, and no involvement of private 'export facilitators.' The entire transaction is completed within four working days from instruction to confirmation of custody. Each step is both Sharia-compliant and resistant to fraud, which, in the context of the gold market, are inseparable requirements.
Ten Mistakes Muslim Investors Make With Gold
- Buying paper instead of metal unallocated exposure fails both the ownership requirement and the safety test.
- 2.Using leverage or CFDs is riba and maysir, and it's the fastest route to losing capital in the market.
- 3. Accepting deferred settlement casually: the default rule is spot; deferrals are the scholar's territory, not the salespeople’s
- 4. Skipping independent assay: overpriced or impure metal is gharar and fraud together.
- 5. Trusting "Islamic" branding: terminology is not structured; check allocation, settlement , and custody in the documents.
- 6. Paying private export fees: unlawful in Kenya and a scam marker under any label.
- 7. Ignoring zakat record-keeping until the liability is painful to reconstruct.
- 8. Leaving gold out of the wasiyya planning: undocumented metal creates estate disputes between heirs and between legal systems.
- 9.Chasing promised returns on a store of value: yield on gold is a scheme's hook, not a market feature.
- 10. Separating the Sharia question from the legal question: the compliant route and the lawful route converge; consulting only one discipline leaves half the risk unexamined.
Frequently Asked Questions
Q1. Is buying physical gold in Kenya halal?
A. Yes, when the purchase is of real, allocated metal settled on the spot and documented properly, which is also the legally safest way to buy.
Q2. Are gold ETFs and gold savings accounts halal?
Generally problematic: most are unallocated claims or derivative exposures that fail the ownership and spot-settlement requirements. Physically backed, fully allocated structures exist in some markets but require case-by-case Sharia review.
Q3. Is trading XAU/USD or gold CFDs halal?
A. No, leveraged speculation on gold prices involves riba (financing) and maysir (gambling-type speculation), and the scholarly consensus is against it.
Q4. Can I buy gold on deferred payment?
A. Positions differ among schools and structures; some murabaha constructions for gold have scholarly support with strict conditions; others prohibit deferral for ribawi items entirely. Do not rely on a seller's assurance; obtain a specific ruling.
Q5. How much zakat do I owe on gold?
A. At 2.5% of the current market value of gold content above the nisab (about 85 grams) held for one lunar year; personal-use jewelry may be treated differently in some schools.
Q6. Is storing gold with a custodian allowed?
A. Yes, allocated, segregated custody against a transparent safekeeping fee is a recognized arrangement; the metal must remain yours, identifiable and unencumbered.
Q7. The dealer says the deal is "Islamic"; is that enough?
A. No. Check the documents: specific allocated metal, spot settlement, no lending of your gold, no promised yield. Vocabulary is marketing; structure is compliance.
Q8. Does buying gold in Kenya create legal risks for a foreign Muslim investor?
A. The legal risks of dealer fraud, unverified metal, and unlawful export channels are identical to those of every foreign buyer, which is why the verification steps in our companion guides apply with full force.
Q9. What happens to my Kenyan gold when I die?
A. It passes under Islamic inheritance rules administered alongside Kenyan law, a wasiyya within the one-third limit, faraid shares for heirs, and a grant process for the estate. Plan it with both your scholars and Kenyan counsel.
Q10.Where do I get a reliable Sharia ruling on my planned transaction?
A. From qualified scholars with Islamic finance expertise, ideally with an institution or advisory board behind them and in parallel from Kenyan counsel on the legal structure. The two reviews together are the complete answer.
How We Can Help
At Anyega Osiemo & Company Advocates, we advise Muslim investors at the intersection of Kenyan law and Sharia compliance: verification of dealers and metal, structuring spot-settled purchases and allocated custody, lawful export handling, estate and wasiyya planning for Kenyan assets, and recovery where non-compliant or fraudulent schemes have caused loss. We work alongside our clients' Sharia advisers; the legal structure and the religious ruling each have their own authority, and our role is to ensure the documents honor both
Disclaimer: This article is general legal information, not legal advice. For guidance on your specific situation, book a consultation with our advocates.