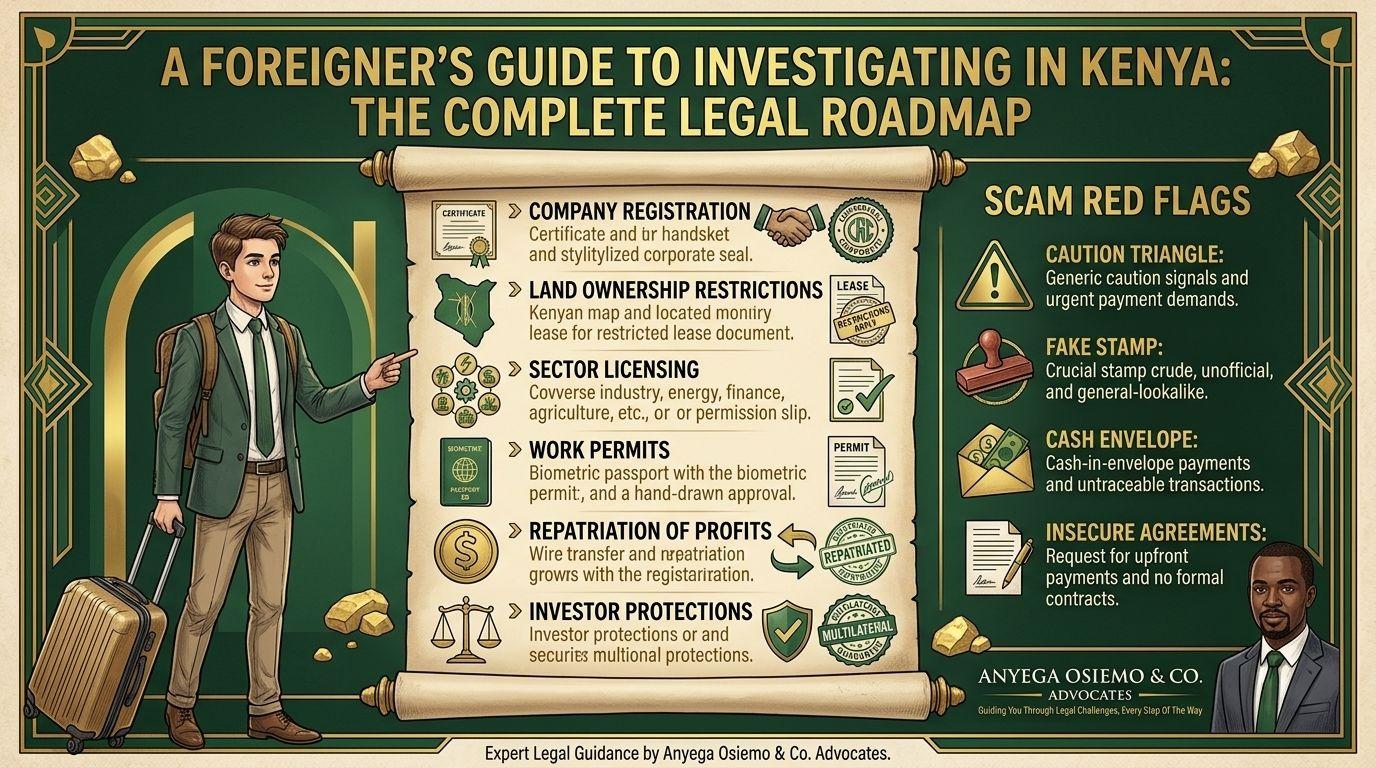
Kenya is regarded as East Africa's leading investment destination, with a common-law legal system, an experienced commercial judiciary, developed capital markets, and access to the EAC and COMESA regional blocs. The legal framework allows foreign investors to own companies outright, acquire long-term leasehold interests in land, and repatriate profits, subject to applicable rules. Those rules differ significantly from those in many other jurisdictions, so the legal and regulatory details require careful attention to avoid costly errors.
This guide addresses the key legal and structural considerations foreign investors must resolve before investing, beginning with the appropriate investment vehicle and then moving through permissible ownership, required personnel and permits, capital movement, and dispute protections.
Can Foreigners Invest in Kenya? Yes With Structure
Kenya's Constitution protects the right to acquire and own property, and the framework built around the Investment Promotion Act treats foreign investors as permitted participants rather than tolerated guests. There is no general foreign-investment screening, no mandatory local partner for ordinary businesses, and no general minimum capital to incorporate.
These rules matter most in land, regulated industries, and the employment of foreign personnel. Each area requires careful legal planning, and the sections that follow address them in detail.
Registering a Company in Kenya as a Foreigner
The standard vehicle is a private limited company under the Companies Act, 2015, and foreigners may hold 100% of the shares, with no local shareholder required.
The practical details:
- Directors: at least one natural-person director; non-residents can serve without restriction.
- Company secretary: every company is required to appoint a company secretary, who must perform the statutory compliance functions.
- Registered office in Kenya, typically provided by your advocates or a corporate-services firm.
- KRA PINs: the company, its directors and shareholders need Kenya Revenue Authority PINs; non-residents obtain theirs with passport documentation through KRA's processes.
- Beneficial ownership disclosure: companies are required to maintain a register of beneficial owners, and significant shareholdings must be disclosed. Nominee structures used to obscure ownership are no longer permitted under Kenyan law.
- Company registration is conducted through the eCitizen platform. Properly prepared applications are typically processed within several days to a few weeks. Opening a bank account is a separate process that involves its own due diligence requirements.
- A foreign company may register a branch in Kenya, but this exposes the parent company directly to Kenyan liabilities. In practice, banks, landlords, and regulators generally prefer to deal with a locally incorporated entity. Branches are typically suitable for short-term or defined projects, while subsidiaries are more appropriate for ongoing operations.
The costs of incorporation are relatively modest, consisting of government fees and professional charges. However, obtaining proper legal structuring advice at the outset is essential, as correcting an inappropriate structure at a later stage is significantly more costly.
Land: The Area Where Foreigners Face Hard Limits
Land law is where foreign investors most frequently make errors, often by assuming that the legal rules of their home jurisdiction apply in Kenya. The rules below show why that assumption can be costly. If this happens, re-check the governing legal regime before any acquisition so the transaction can be restructured before commitments are made.
- No freehold for non-citizens. Under Article 65 of the Constitution, non-citizen individuals and foreign-owned companies alike cannot hold land in freehold. They may hold leasehold interests of up to 99 years, which are marketable, mortgageable, and, in practice, renewable, but the distinction shapes deal structure and exit planning.
- Agricultural land is a separate regime. The Lands Control Act tightly controls dealings in agricultural land, and non-citizens are effectively excluded absent a presidential exemption. Foreign agribusiness investors therefore structure through long leases, management contracts and joint ventures rather than direct ownership, and if a structure quietly hands agricultural freehold to a foreigner, unwind it early, before a dispute or nullity follows.
- Comprehensive due diligence is essential in every land acquisition. This includes conducting an official registry search, confirming payment of land rates and rent, verifying the seller's identity and legal capacity, obtaining spousal consent where required, and reviewing the chain of title, particularly for land that has previously changed hands. The existence of forged or double-allocated titles in the market makes these steps critical.
- The lease terms require careful negotiation and review. The duration, renewal provisions, rent escalation clauses, user covenants, and rights of assignment or subletting should be scrutinized with the same diligence as a freehold purchase, as these terms determine the substantive value of the interest acquired.
Structuring Choices Compared: Subsidiary, Branch or Joint Venture
The vehicle question is usually answered too fast. The realistic options are compared below, starting with the most common structures before moving to more situational choices.
- Wholly-owned subsidiary: the default, for good reasons: limited liability, local credibility with banks and government, clean separation of Kenyan risk, and a straightforward licensing platform. Costs: the full Kenyan compliance load (secretary, audits, annual returns, tax filings) must actually run, not merely exist.
- Branch of a foreign company: lighter in some respects, but with direct parent exposure, and counterparties prefer local entities. Suited to market-testing or defined projects, rarely to permanent operations.
- Joint venture with a local partner: sometimes commercially essential for land access, distribution, and political economy. But the JV documents, not the relationship, must carry the deal: deadlocks, reserved matters, exit rights, non-competes and change-of-control provisions are the clauses that matter. A structure that appears cost-effective at the time of incorporation but proves costly in a dispute is not appropriate, regardless of initial savings.
Sector-Specific Rules Worth Knowing
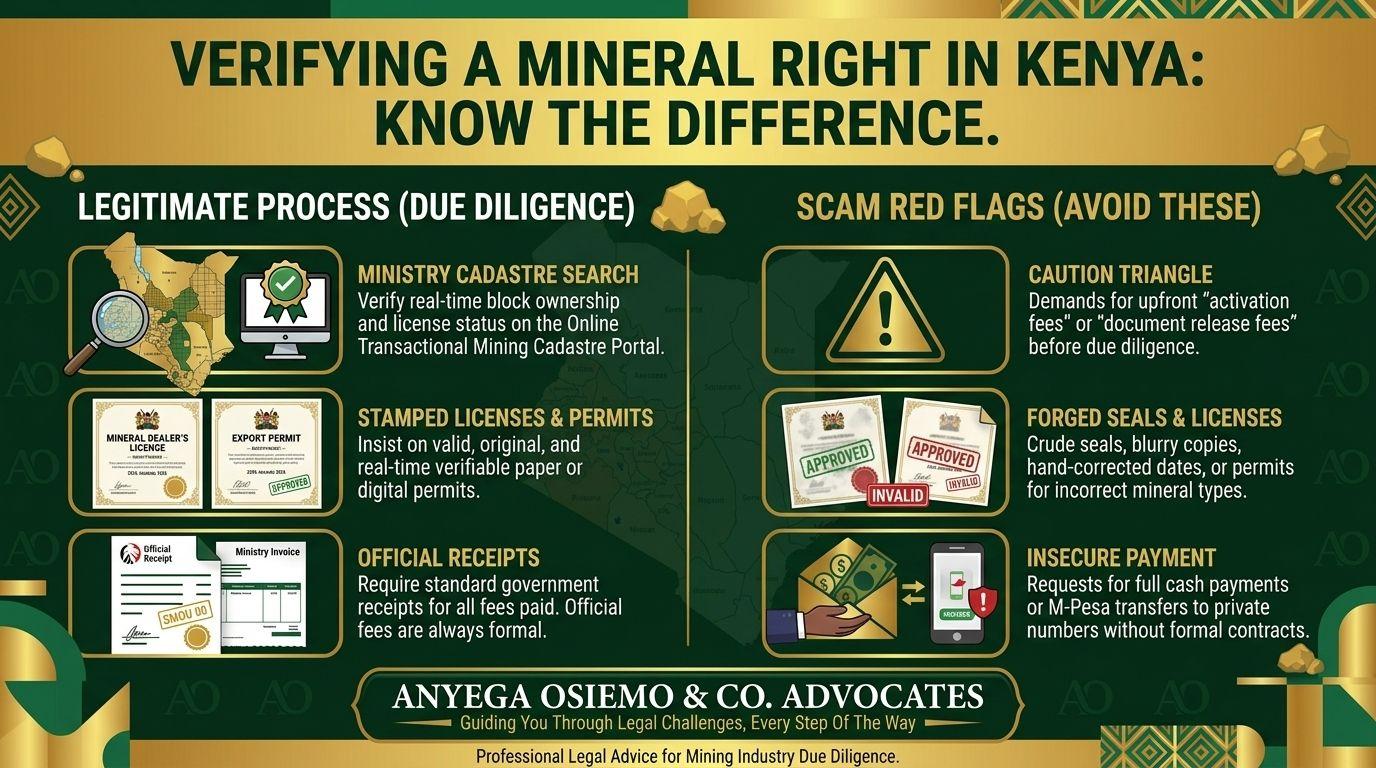
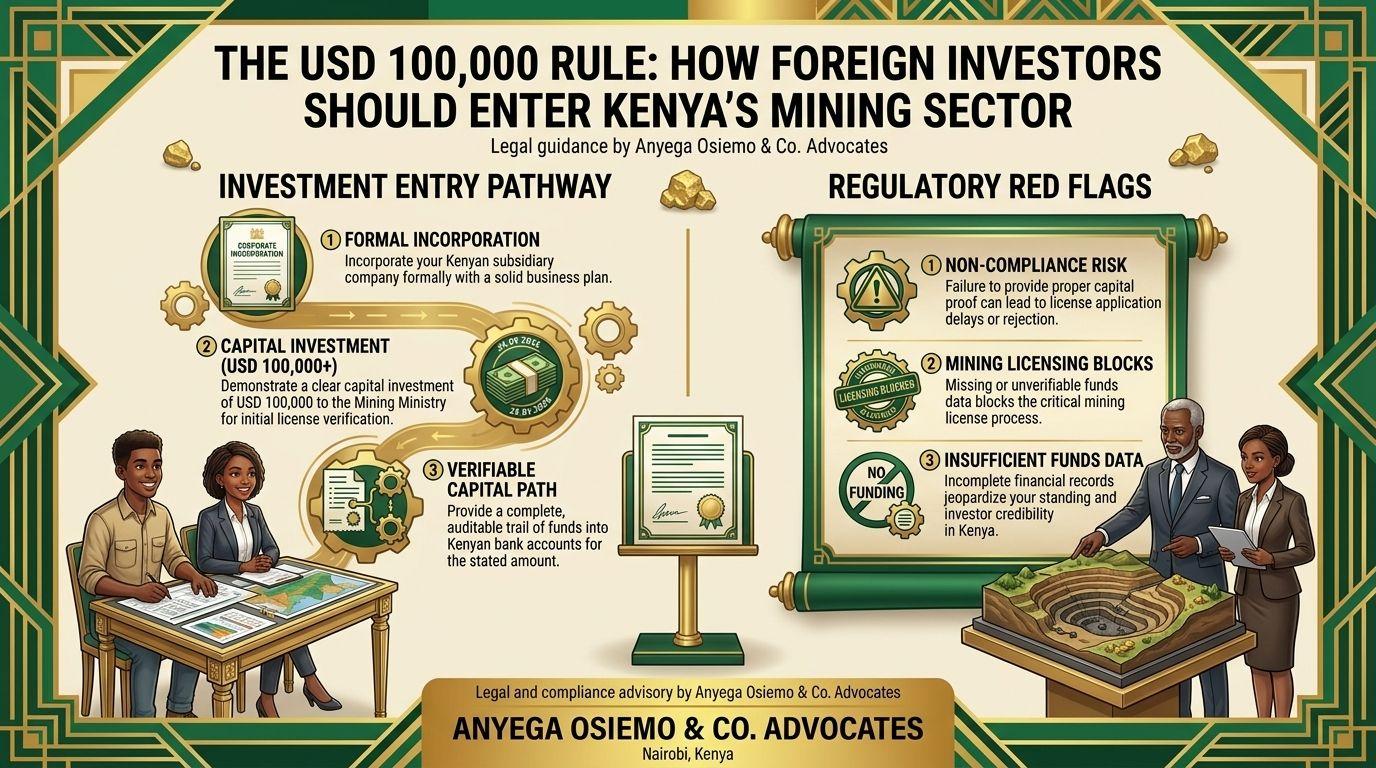
- Mining and minerals: foreign investors are welcome under the Mining Act, 2016 framework, with a minimum investment of USD 100,000 to qualify for mineral rights. The licensing tiers (license vs permit vs dealer's license) determine what you may actually do. Counterparty verification in this sector is a discipline in its own right.
- Financial services, telecoms, energy, and aviation: each carries sectoral licensing with local incorporation, capitalization, or control requirements, and none should be assumed from the general company framework.
- Special Economic Zones and export processing zones: qualifying activities enjoy reduced corporate tax rates, VAT relief and simplified regimes large enough to change project economics, and worth modelling before defaulting to a standard structure.
- Competition law: mergers and acquisitions above threshold require Competition Authority notification before implementation; deal timetables must build this in.
Getting People on the Ground: Work Permits
Foreign nationals who intend to work in Kenya are required to obtain a work permit, most commonly a Class D permit issued by the Ministry responsible for immigration. Investors often underestimate the requirements and implications of this process.
- Permits attach to specific roles and employers; a director "helping out" operationally without a permit is working illegally.
- Processing takes months and requires demonstrated qualifications and a justified role.
- Short assignments may fit special passes; defendants need their own passes; every track has its own rules and fees.
- Liability for employing foreign nationals without valid work permits attaches to both the company and the individual concerned. If this issue arises during disputes, regulatory inspections, or license renewal processes, regularize the permits immediately and address the compliance gap without delay.
Money In, Money Out
Kenya operates a liberal foreign-exchange regime, administered by the Central Bank of Kenya. Compliance with documentation requirements is essential. If documentation is incomplete, recover by assembling the required records before attempting any transfer or repatriation.
- Capital should be brought into Kenya through the formal banking system and properly registered, which serves as the modern equivalent of the certificate of capital importation. This documentation is necessary to establish the right to repatriate capital and profits. Failure to comply with these requirements may result in significant difficulties at the time of exit, which may be costly or impossible to remedy.
- Dividends are repatriated after tax, against audited accounts and board approvals.
- Transfer pricing and thin-capitalization rules govern related-party payments; intra-group loans and service fees must be defensible from day one, not reconstructed at audit.
- Withholding taxes apply to management fees, royalties, interest, and service payments. These should be factored into financial models from the outset.
- Obtaining Kenya Revenue Authority (KRA) clearance upon exit is necessary to conclude the investment cleanly. Failure to secure this clearance may adversely affect future dealings in Kenya.
Investor Protections
Kenya offers real, enforceable protections: constitutional property protection with compensation on compulsory acquisition; a commercial division of the High Court with genuine expertise; membership of ICSID; the Nairobi Centre for International Arbitration (NCIA); and recognition of foreign arbitral awards under the New York Convention, which Kenya has implemented. A network of bilateral investment treaties adds treaty protections for covered investments. The drafting lesson is simple and bears repeating: put arbitration clauses in your contracts at NCIA or another sensibly seated institution because enforcement predictability is the whole game, and the New York Convention machinery is what makes an award worth the paper it is written on.
The Acquisition Sequence: A Sensible Order of Operations
Foreign investors may incur losses by taking necessary steps in the wrong order. The following is a recommended order of operations:
- Legal mapping before term sheets: what you can own, what needs a license, what permits your people need, modelled on your actual business.
- 2 . Entity and tax structuring: incorporation, PINs, banking, and the capital-registration documentation that protects repatriation.
- 3 . Asset due diligence for land or operating businesses: searches, valuations, litigation, liens, employment and tax health run by your own advisers, not the seller's.
- 4. Contracting sale or shareholders' agreements with enforceable dispute clauses, conditions precedent reflecting due diligence, and warranties that survive completion.
- 5. Regulatory completion:n sector licenses, competition notification, work permits sequenced so no permit gates the launch unprepared.
- 6 . Operational compliance from month one: transfer pricing, employment contracts, data-protection registration, statutory filings.
- 7 . Exit architecture reviewed on entry:ry tag-along, drag-along, put options and pre-emption save the ruinous renegotiations that otherwise greet an exit.
Where Foreign Investors Actually Get into Trouble: Real Dispute Patterns
The theory is easy; the disputes have a sameness worth learning from:
- Land fraud and duplicate allocations: plausible sellers, perfect documents, no title. The antidote is patient, official verification, every time.
- Shareholder deadlocks: 50/50 ventures without deadlock mechanics; the business freezes while the parties litigate.
- Informal promises treated as obligations: "the county will support us" documented nowhere; personnel change and the support evaporates.
- Employment informality: key staff without contracts or permits; a dispute converts a management problem into liability.
- Acquired liabilities: a purchased company carrying tax arrears, employment claims, or litigation, priced at zero.
- No workable forum clause: silence means Kenyan courts on their timeline; arbitration means enforceability on yours.
Each of these issues is relatively inexpensive to prevent through careful drafting, but can be costly to resolve through litigation.
Ten Mistakes Foreign Investors Make in Kenya
- Buying agricultural freehold through nominees is unenforceable and a magnet for disputes.
- 2. Skipping capital-registration documentation: exit money without a paper trail.
- 3. Assuming a local partner is legally required; it usually is not; choose partners for value.
- 4 . Directors "working" without permits; the company is fined too.
- 5 . Weak land due diligence:e a forged title survives until you sell or develop.
- 6. No arbitration clause; trial litigation on Kenyan timelines is the default nobody chose.
- 7. Ignoring SEZ modelling: ignoring the tax differences changes project economics.
- 8 . Related-party arrangements without transfer-pricing discipline; KRA audits find them.
- 9. Structuring around the Mining Act minimums:s non-citizens need the USD 100,000 demonstration for mineral rights.
- 10. Structures that depend on "friendly" officials:s anything that matters must work on the documents alone.
Frequently Asked Questions
Q1. Can a foreigner own 100% of a Kenyan company?
A. Yes. The Companies Act imposes no local-ownership requirement for ordinary private companies; sectoral licenses (mining, financial services, telecoms) carry their own conditions.
Q2. Can foreigners buy land in Kenya?
A. Only leasehold, up to 99 years and not agricultural land except through tightly controlled structures. Foreign-owned companies count as foreigners for these purposes.
Q3. Is there a minimum investment to invest in Kenya?
A. No general minimum for incorporation or ordinary business. Specific regimes set their own thresholds, with USD 100,000 for foreign mineral rights holders under the Mining Act being the best-known.
Q4. How long does company registration take?
A. Days to a couple of weeks on eCitizen with prepared documents and PINs; add time for bank account opening and sector permits.
Q5. Can I get Kenyan residence as an investor?
A. Investor-class permits exist, and citizenship-by-investment frameworks have been under active legislative development; take current advice on available tracks.
Q6. How do I repatriate profits from Kenya?
A. Through the banking system, from taxed profits, with the capital-registration trail in place. Documented repatriation is routine; undocumented repatriation is the problem.
Q7. Do I need to live in Kenya to run my company?
A. No, non-resident directors are lawful, but you need permitted people on the ground doing the actual work, and a functioning local compliance structure.
Q8. What taxes will my Kenyan company pay?
A. Corporate income tax at the standard or SEZ rates, VAT where applicable, withholding on cross-border payments, and payroll taxes modelled properly; none of these is a surprise; discovered late, all of them are.
Q9. How do I protect my investment if a dispute arises?
A. Contractual protections, a sensible seat of arbitration, treaty coverage where available, and local counsel who litigate as well as they advise.
How We Can Help
At Anyega Osiemo & Company Advocates, we structure foreign investments into Kenya end-to-end: incorporation and shareholder frameworks, land acquisition and leasing with full due diligence, sector licensing strategy, work permit management, tax-efficient structuring and SEZ modelling, and dispute-resolution architecture built around enforceable arbitration.
Before committing capital, contact us. The most cost-effective legal advice is obtained at the outset of an investment.
Disclaimer: This article is general legal information, not legal advice. For guidance on your specific situation, book a consultation with our advocates.