The primary source of company litigation is not the market or regulatory environment, but the relationship between shareholders. Disputes commonly arise between co-founders over strategic direction, among family members who inherit shares without a shared vision, or with investors who later discover that equal shareholding does not guarantee effective governance. Most of these disputes could have been prevented at minimal cost through a properly drafted shareholder agreement (SHA), executed at the outset of the business relationship.
A shareholder agreement (SHA) is a private contract among a company's shareholders, which operates in conjunction with, and in certain respects may override, the articles of association. While the Companies Act provides the default legal framework for companies, the SHA allows shareholders to tailor the governance of the company to their specific needs and relationships. This guide examines seven critical clauses that prevent common shareholder disputes, with particular reference to Kenyan legal practice.
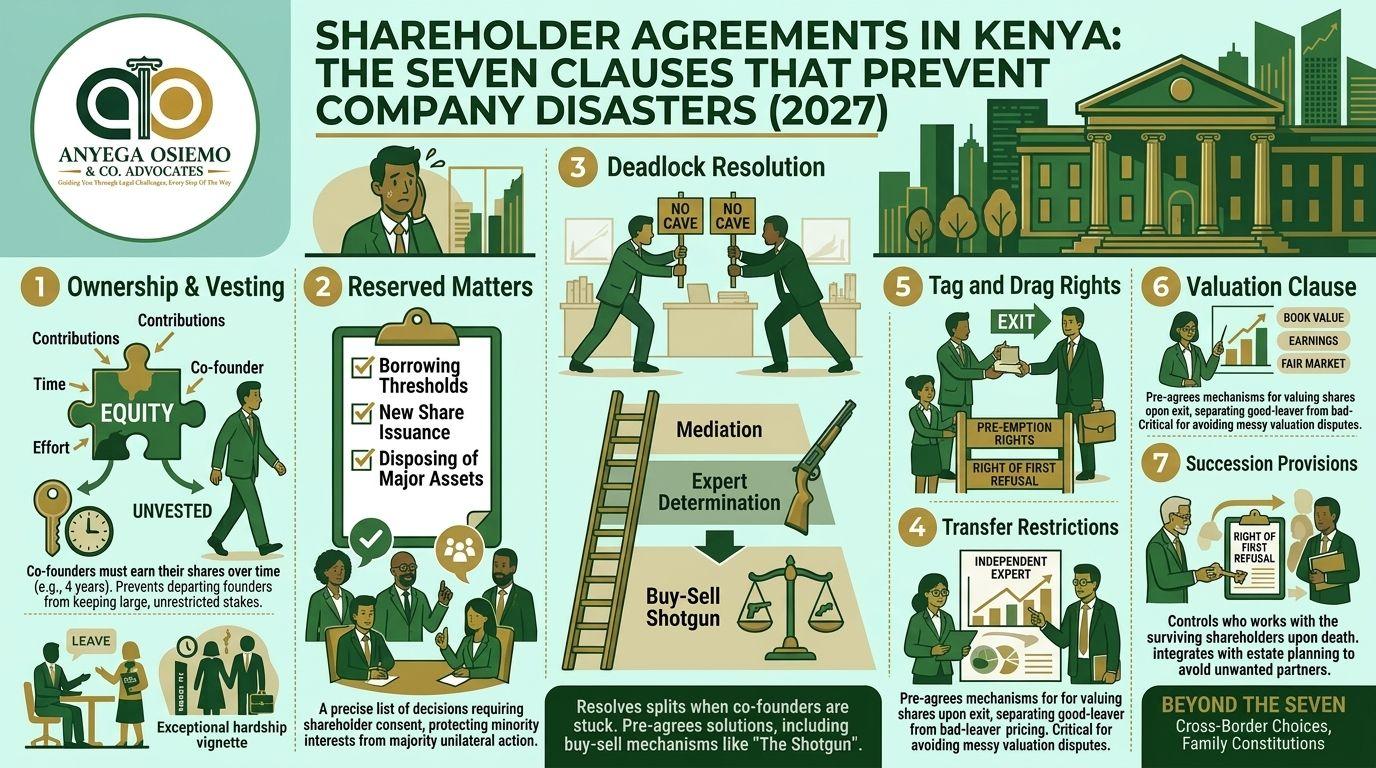
1. Ownership and Vesting: Who Earns What, Over Time
A common error among founders is to allocate equity equally at the inception of the company, without regard to future contributions or departures. A properly drafted SHA addresses this by providing for vesting of shares over a defined period, typically four years with a one-year cliff. This ensures that a co-founder who leaves early forfeits unvested shares, while those who remain and contribute retain their earned equity. In Kenya, these vesting structures are often adopted from international practice, but must be carefully integrated with the share register and articles of association to ensure that unvested shares revert appropriately. Failure to include vesting provisions can leave departed founders with significant equity, complicating future investment and exit transactions.
2. Reserved Matters: The List That Requires Everyone
While the board of directors is responsible for the day-to-day management of the company, the SHA specifies certain reserved matters that require the consent of shareholders, often by a specified majority or unanimity. Typical reserved matters include borrowing above certain thresholds, issuing new shares, disposing of significant assets, altering the nature of the business, entering into related-party transactions, making senior appointments, and approving budgets. The reserved matters clause protects minority shareholders by ensuring that significant decisions cannot be made unilaterally by the majority. In practice, companies that suffer from unilateral decision-making often lack a comprehensive reserved matters provision.
3. Deadlock Resolution: What Happens When Nobody Blinks
Two equal shareholders, opposite positions, no casting vote: the deadlock clause is the difference between a resolved dispute and a dying company. The menu, in ascending ferocity: escalation to principals with a deadline; mediation; expert determination for technical questions; buy-sell mechanics (the "shotgun" one side names a price per share, the other chooses whether to buy at that price or sell at it, guaranteeing a fair offer); and, ultimately, the exit provisions below. At this stage, the agreement should specify the trigger, the start clock, and the next step if the deadlock is not resolved.
4. Transfer Restrictions: Who Gets In, and How
Shares in a private company are relationships, not commodities; the SHA controls their movement. The standard architecture:
- Pre-emption rights: a shareholder wishing to sell must first offer to existing shareholders pro rata, at the offered price, before outsiders enter.
- Right of first refusal: the company or shareholders may match any third-party offer.
- Permitted transfers: carve-outs for family, group companies and estate transfers, so the restrictions police outsiders rather than imprison insiders.
- Lock-ins: periods often tied to investment milestones during which nobody sells.
Without these restrictions, a shareholder may transfer a significant portion of shares to an external party, including a competitor, without the consent of the remaining shareholders. The articles of association alone may not provide adequate protection against such transfers. These provisions therefore keep control within the intended group and prevent unwanted outsiders from entering unexpectedly.
5. Tag and Drag: Protecting Minorities, Enabling Exits
Tag-along and drag-along rights are essential provisions that address the interests of both majority and minority shareholders in exit scenarios. Tag-along rights ensure that minority shareholders have the opportunity to participate in a majority's sale of shares on the same terms, thereby preventing them from being left in a company controlled by new owners. Drag-along rights, conversely, allow a majority of shareholders (typically at a specified threshold, such as 75%) to require all shareholders to sell their shares to a third-party buyer on the same terms, facilitating a clean exit. These provisions are frequently required by investors and should not be omitted.
A comprehensive shareholder agreement should address, in advance, the mechanisms for valuing shares upon exit, including whether valuation will be determined by an independent expert, a predetermined formula, or book value (noting that book value is often inappropriate for growing companies). The agreement should specify the circumstances under which shareholders may be compelled to sell or may require others to sell, and should distinguish between good-leaver and bad-leaver scenarios, with corresponding pricing mechanisms. Provisions for earn-outs, deferred consideration, and post-departure non-compete and non-solicitation obligations should also be included. The agreement should then state how the valuation process is initiated, who appoints the valuer, and when payment or transfer occurs. Valuation clauses that are clear and specific are essential, as disputes over valuation are common and often turn on contested formulae.
6. Succession: The Clause Everyone Forgets
Upon the death of a shareholder, the default legal position is that the shares pass to the deceased's estate and heirs, who then acquire the associated shareholder rights. This can result in the remaining shareholders being required to work with individuals they did not select. Succession provisions in the SHA can address this by providing for insurance-funded buy-out arrangements, pre-agreed mechanisms for transfer of shares upon death, and rights of first refusal for surviving shareholders. The agreement should also set out who gives notice of death, how the transfer process begins, what deadline applies, and what the surviving shareholders must do next. It is important that these provisions are coordinated with the shareholder's personal estate planning to avoid conflicts between the SHA and the will.
7. Beyond the Seven: Cross-Border, Family and Dispute Architecture
Three overlays complete the picture. Cross-border shareholders add governing law, forum, and arbitration choices; the New York Convention machinery behind Kenyan-seated arbitration makes it the professional default for ventures with foreign shareholders. Family businesses benefit from constitutions that separate family from firm: employment terms, dividend policy, and dispute forums that are not Christmas dinner. Dispute resolution clauses should run throughout: escalation ladders, mediation windows, and a forum chosen deliberately, not by template default. Each agreement should say who starts the process, what happens if no agreement is reached, and which forum or mechanism applies next.
8. A Worked Example: The Startup That Skipped the Meeting
Consider the following example: three founders each hold an equal share of a company, but no shareholder agreement is in place. In the first year, one founder becomes inactive but retains their equity. In the second year, a potential investor conducts due diligence and identifies that the inactive founder holds an unvested and unrestricted 33% shareholding. The investor requires the implementation of vesting and transfer restrictions, leading to complex negotiations and strained relationships. By contrast, if a shareholder agreement had been executed at the outset, providing for vesting, transfer restrictions, reserved matters, deadlock resolution, and tag-along and drag-along rights, these issues would have been avoided.
Ten Mistakes in Shareholder Agreements
- No agreement at all: the most common, and the root of the rest.
- Template without tailoring: your business, investors, and exit are not generic.
- Vesting omitted: dead equity poisons cap tables and exits alike.
- Reserved matters too narrow; unilateral borrowing and dilution quietly destroy companies.
- No exit path: if the relationship fails, the company needs a clean way out.
- Transfer restrictions that forget permitted transfers: families and estates trapped by their own document.
- Valuation by vibes: "fair value" without a mechanism is an invitation to litigate the obvious.
- No good-leaver/bad-leaver distinction: the departing saboteur is priced like the departing saint.
- Succession: the default heir is the succession process, not the person you'd have chosen.
- It is common for the shareholder agreement drafted at incorporation to remain unreviewed, even as the company evolves and changes significantly. It is essential to review and, where necessary, update the shareholder agreement at every funding round and whenever there is a major change in the company’s structure or operations.
Frequently Asked Questions
Q1. Is a shareholders' agreement legally binding in Kenya?
A. Yes, as a contract between its parties, enforceable under Kenyan contract law, sitting alongside the articles and operating as agreed between the signatories.
Q2. What is the difference between articles and a shareholder agreement?
A. The articles of association serve as the company’s public constitution and are binding on the company itself. In contrast, the shareholder agreement is a private contract between the shareholders. The two documents interact, as the shareholder agreement often requires shareholders to exercise their rights under the articles in a manner consistent with its terms.
Q3. Do I need one for a two-person company?
A. It is particularly important in the case of a two-person company. Companies with equal shareholders are especially prone to deadlock and disputes. A shareholder agreement is cost-effective because it is entered into before any issues arise, providing a clear framework for resolving potential conflicts.
Q4. Can a shareholder agreement override the Companies Act?
A. No, statutory rights and protections provided by the Companies Act cannot be contracted away by a shareholder agreement. The shareholder agreement operates within the framework of the Act and may supplement it by providing additional mechanisms where the Act is silent.
Q5. What happens if we have no SHA and a dispute arises?
A. In the absence of a shareholder agreement, the parties must rely on the articles of association, the Companies Act, and negotiation, in that order. In practice, most agreements reached after a dispute are settlements determined by the relative bargaining power of the parties, rather than by careful planning.
Q6. Can we amend a shareholder agreement later?
A. Yes, a shareholder agreement can be amended in accordance with its own amendment provisions, which typically require consent thresholds that reflect the interests at stake. It is prudent to consider amending the agreement at each funding round, when an exit is being contemplated, or when there are significant changes in the family or among the shareholders.
Q7. What is a shotgun clause?
A. A shotgun clause is a buy-sell mechanism in which one shareholder sets a price per share, and the other shareholder must choose either to buy at that price or to sell their shares at that price. This structure is intended to ensure that the offer made is fair, as the party making the offer must be willing to accept either side of the transaction.
Q8. Should family businesses have shareholder agreements?
A. Yes, family businesses should have shareholder agreements, and these should include specific provisions for family governance. Such provisions should address the separation of ownership, employment, and family roles, and should also provide for the coordination of inheritance matters.
Q9. Do investors require shareholder agreements?
A. Serious investors typically require shareholder agreements that include provisions on vesting, anti-dilution, board rights, tag-along rights, and exit arrangements. These are standard terms in investment transactions. Presenting a well-drafted shareholder agreement demonstrates professionalism and can expedite the due diligence process.
Disclaimer: This article is general legal information, not legal advice. For guidance on your specific situation, book a consultation with our advocates.